The $800 Billion Question: Which APAC Markets Will Win the Data Center Talent War?
While APAC’s data centre boom is attracting record capital, a looming shortage of skilled engineers threatens to stall growth. Success in the next decade will belong to the markets that solve the talent equation first.
DC Jobs · Editorial Team
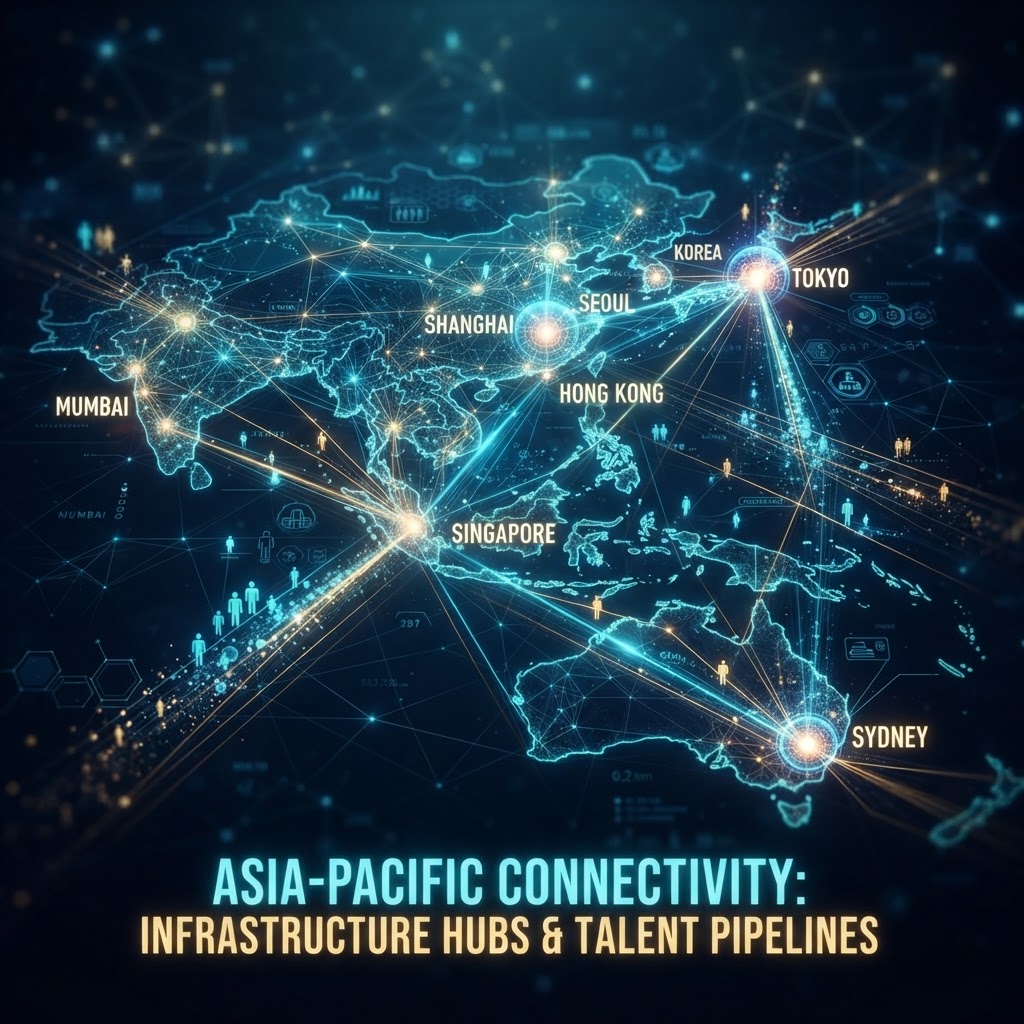
The Talent Bottleneck in APAC
Capital is no longer the bottleneck for data centre growth in APAC — people are. Every market in the region has a pipeline of announced capacity, a queue of hyperscale and colocation projects, and a story about becoming "the next big hub." But announced megawatts and available, qualified talent are two very different curves, and in most APAC markets they are moving in opposite directions. The country that wins the next decade of digital infrastructure won't necessarily be the one with the most capital committed — it will be the one that solves its talent equation first.
The Gap Between Capacity Plans and Workforce Reality
Every regional capacity forecast tells a growth story. Very few of those forecasts are paired with an equally rigorous workforce plan. That mismatch is the real story of APAC's data centre boom: markets are competing to announce gigawatts, but almost none are competing — visibly, at least — to build the technician, engineering, and operations talent base required to run them.
This matters because data centres are not "build it and walk away" assets. A hyperscale campus needs:
- critical facilities engineers
- mechanical and electrical technicians
- controls specialists
- increasingly liquid-cooling-literate operations staff
The scale of what's coming is significant: APAC is projected to add over 31.4 GW of installed data centre power capacity between 2025 and 2030, according to Arizton's APAC Data Center Market Landscape report, with China contributing more than 18.2 GW of that, followed by Malaysia (over 3 GW) and India (over 2.4 GW). Those numbers are a useful signal of where demand will concentrate — but they say nothing about whether the local labour market can staff that demand.
Established Hubs: Deep Pipelines, Rising Saturation
Markets like Singapore, Tokyo, and Sydney built their talent pipelines over 15-plus years of steady data centre investment. They have vocational programs, migration pathways for skilled engineers, and a critical mass of experienced operations staff who've cycled through multiple employers. That depth is a real advantage.
But depth is not the same as slack. In mature markets, experienced facilities and critical infrastructure professionals are already being re-recruited between operators rather than newly trained — a sign of a market closer to full utilisation of its existing talent pool than a market with room to absorb the next wave of capacity without wage inflation or longer time-to-hire. Employers in these hubs increasingly compete less on headline capacity and more on retention: career progression, specialised training, and compensation structured to reflect scarce skills rather than generic IT roles. If you're evaluating offers in one of these markets, it's worth benchmarking your specific technical specialisation against current postings rather than generic IT salary data, since generalist and specialist rates in mature markets are diverging fast.
Emerging Hubs: Capacity Outpacing the Pipeline
The more interesting — and riskier — story is in the emerging build-out markets: parts of Malaysia, Indonesia, India, and secondary cities across the region that are absorbing hyperscale investment that outgrew the established hubs' land, power, or regulatory capacity. These markets can offer real career upside for professionals willing to relocate or for local talent willing to fast-track into critical roles, precisely because supply hasn't caught up with demand.
The risk sits with employers, not candidates. Operators moving into these markets often underestimate how long it takes to build a genuinely deep bench of critical facilities skills locally — commissioning experience, BMS/EPMS fluency, and the judgment that comes from having managed a live incident, not just a training simulation. That's why many projects in fast-growth markets lean heavily on expatriate or regionally rotated senior staff in the first several years of operation, even as they invest in local training pipelines. For professionals, this creates a genuine opportunity: emerging markets are often more willing to accelerate career progression for people who can demonstrate hands-on competence, because the alternative — leaving a role unfilled — is more costly than in a saturated market.
Where the Competition Will Actually Be Fiercest
If you map projected capacity growth against realistic pipeline output — not headcount targets, but graduates, apprenticeships, and migration flows actually producing qualified critical infrastructure staff — the fiercest hiring competition by 2030 will likely concentrate in markets attempting the fastest capacity ramp without a proportional investment in workforce development. That combination — high growth, thin pipeline — is where salaries move quickest and where counter-offers become routine.
For candidates, this is the practical takeaway: geography matters less than trajectory. A market with modest current activity but a steep capacity ramp and a visible skills shortage can offer faster career progression than a mature market where roles are plentiful but competition for them is just as intense.
What This Means for Your Next Move
- If you're in a mature market: differentiate on specialisation, not tenure. Liquid cooling, high-density power distribution, and controls integration are the skills commanding premium attention.
- If you're considering an emerging market: weigh the accelerated responsibility against the maturity of the employer's training and safety systems — not every fast-growth site is equally well-run.
- Everywhere: track capacity announcements as leading indicators of hiring demand, not just industry news. A new campus announcement today is a hiring signal 18–24 months out.
Bottom Line
The APAC data centre talent war won't be won by whichever market builds the most capacity — it will be won by whichever markets pair that capacity with a real, funded pipeline of skilled operations and engineering talent. For professionals, that means the smartest career moves right now are less about chasing the biggest headline project and more about reading the gap between announced growth and available skills — and positioning yourself where that gap is widest.
Ready to see where the demand is concentrating right now? Browse live roles across the region on DC Jobs.
Related articles
Japan's Institutional Pivot: What the Shift from Hyperscale to Institutional Capital Means for Local Hiring
Power Before People: What Grid Bottlenecks Mean If You're Job Hunting in APAC Data Centers